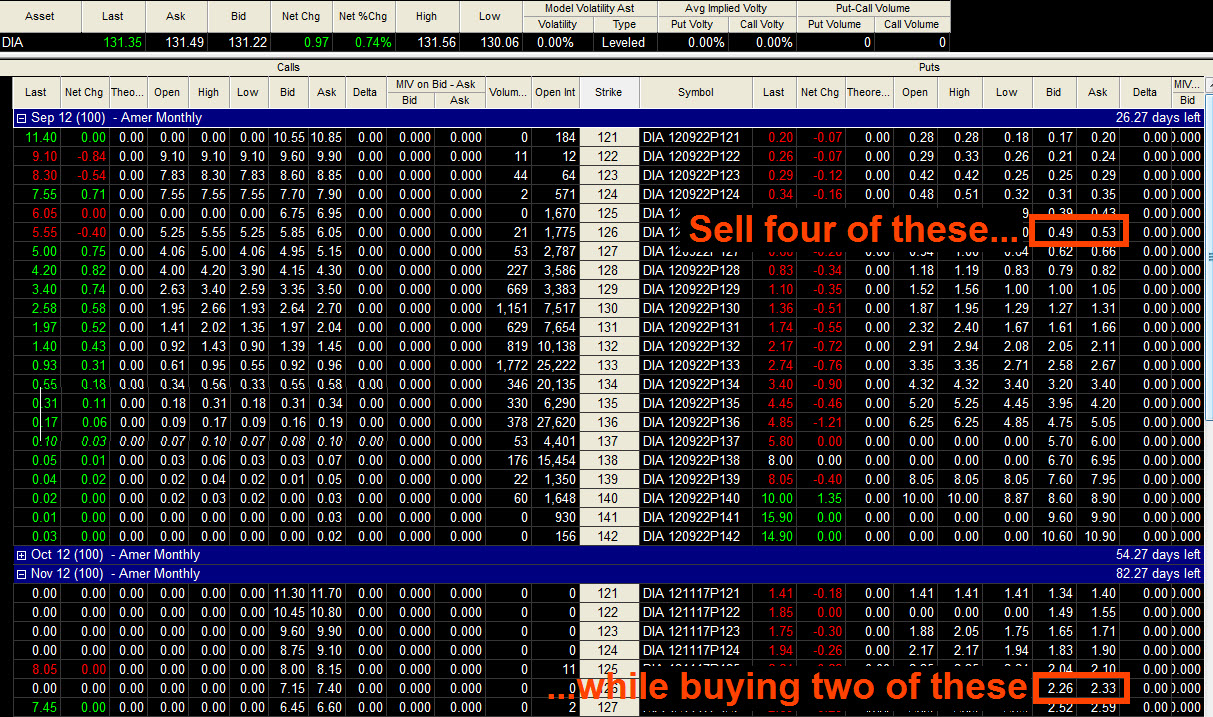
 We hold a tracking position of two September 126 puts with a profit-adjusted cost basis of 0.45. Let’s roll this bearish position into November while we are still ahead on the puts. Accordingly, buy the November 126-September 126 put spread twice for 1.80 or better (see inset). At the same time, sell two additional September 126 puts for 0.50 with six cents’ discretion. We are effectively double-selling the September 126 puts from our position in order to turn a simple long-put position into a calendar spread. The price your receive for the “extra” puts doesn’t matter much, although the spread price of 1.80 should be adhered to. If you were to receive, say, 0.50 when you close out the September 126 puts, the dime over our cost basis would effectively reduce the price of the new spread by a nickel, to 1.75. ______ UPDATE (September 4, 1:20 a.m.): The Sep 126 puts traded as high a 0.64, so I’ll use a 1.70 basis for the spread unless I hear of a less favorable fill in the chat room. Do nothing further for now. _______ UPDATE (October 2): As a low-cost bear play, we simply held onto the November puts after the Septembers went out worthless. The Novs are currently trading for around 0.65, implying a paper loss of $210 on the position thus far. For now, offer two November 122 puts against them for 1.05, good till canceled. This order will fill only if DIA gets whacked, but good. _______ UPDATE (October 17, 8:43 p.m. EDT): We’ll drop this one from the sheets by zeroing out the Nov 126 puts for an additional $130 loss. With DIA up by only a couple of points since we acquired them, the puts are actually still worth about $60, but I’ll “recall” them only if the Dow collapses between now and November 16.