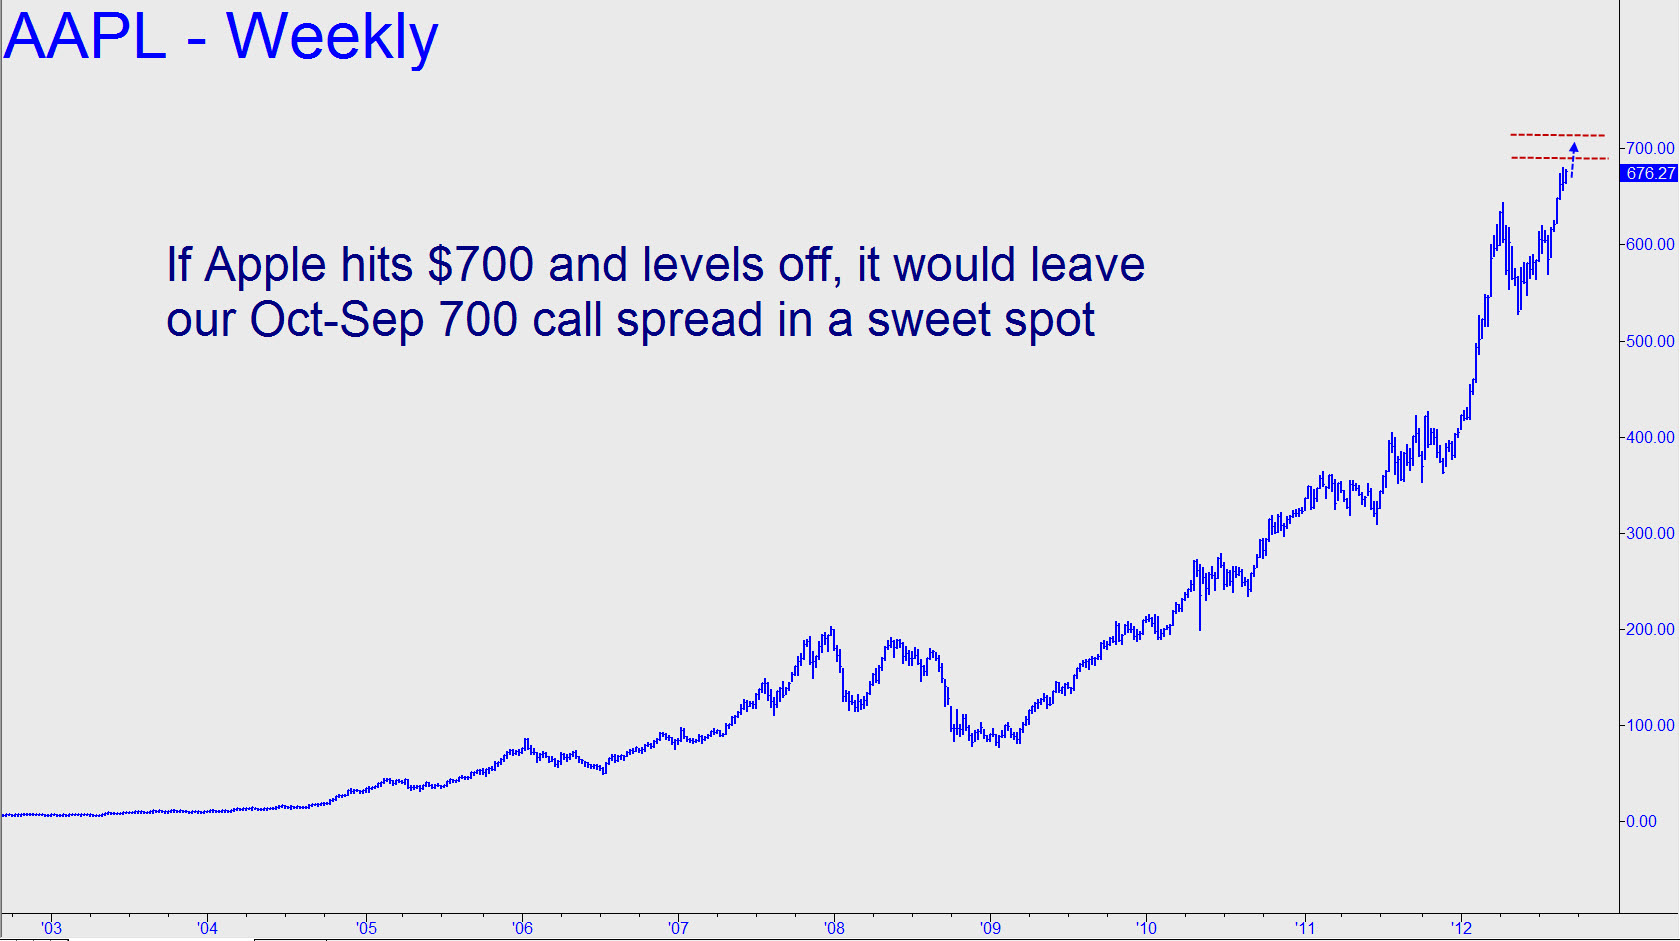
 Over the last two weeks, we’ve constructed an elaborate hedge that consists of eight Dec-Oct 620 put spreads @ 14.00; four short Sep 615 puts @ 6.20; and long two Oct-Sep 700 call spreads @ 10.00. It leaves us ever-so-slightly frontspread and presumably comfortable if AAPL makes its way toward 700 between now and expiration Friday in two weeks. A decline would work for us as well, since it would likely add more value to our put spread than we would lose on the call spread. Meanwhile, and fortunately, the September 615 puts we shorted @ 6.20 look like goners, meaning the entire $2480 we received for them will be ours to keep. That would partially offset the premium we paid for our ten calendar spreads. For now, sit tight. ______ UPDATE (September 11, 12:33 a.m. EDT): Bid 0.50, good-till-canceled, to cover the four September 615 puts we are short. _______ UPDATE (September 13, 1:00 p.m. EDT): The September 615 puts opened at 0.37, so we’ll consider the position closed with a theoretical/actual profit of about $2300 after commissions. Imputing this sum to the eight Dec-Oct 620 put spreads will effectively lower the cost basis to 11.10. We also hold two Oct-Sep 700 call spreads for 10.00 that are currently worth around 11.50. They have the potential to go to around 22.00 by next Friday’s expiration, although realizing full value when we close out the spreads could be tricky.