 With Twitter getting hammered yesterday, apparently by investors grown increasingly distressed over the firm’s vaporous revenue model, it seems only a matter of time before they discover that LinkedIn’s business model and methods are arguably even more dubious. I say this from personal experience, since my email box has been filling up lately with daily exhortations from LinkedIn to ‘congratulate’ someone or other on the ‘anniversary’ of that person’s entry into business or full-time employment. It is understandable that LinkedIn should want to keep itself visible with constant reminders of the company’s existence to millions of subscribers whose interest in the service might otherwise wane to nothingness. But how lame can you get? LinkedIn overworks dozens of such messages to serve this end, resulting in perhaps half-a-dozen emails each day to subscribers who couldn’t care less.
None of this seems to trouble the greedy, malfeasant speculators on Wall Street who have bid the stock above $200 with Other People’s Money. That equates to a capitalization of $25 billion — as absurd a valuation as any the Street has promoted since the dot-com bubble, or perhaps even since Tulipmania. Do these wild-eyed jackasses even care whether a web-based company that purports to be indispensable to businesspeople is really no more than a self-propagating, viral scheme? Evidently not.
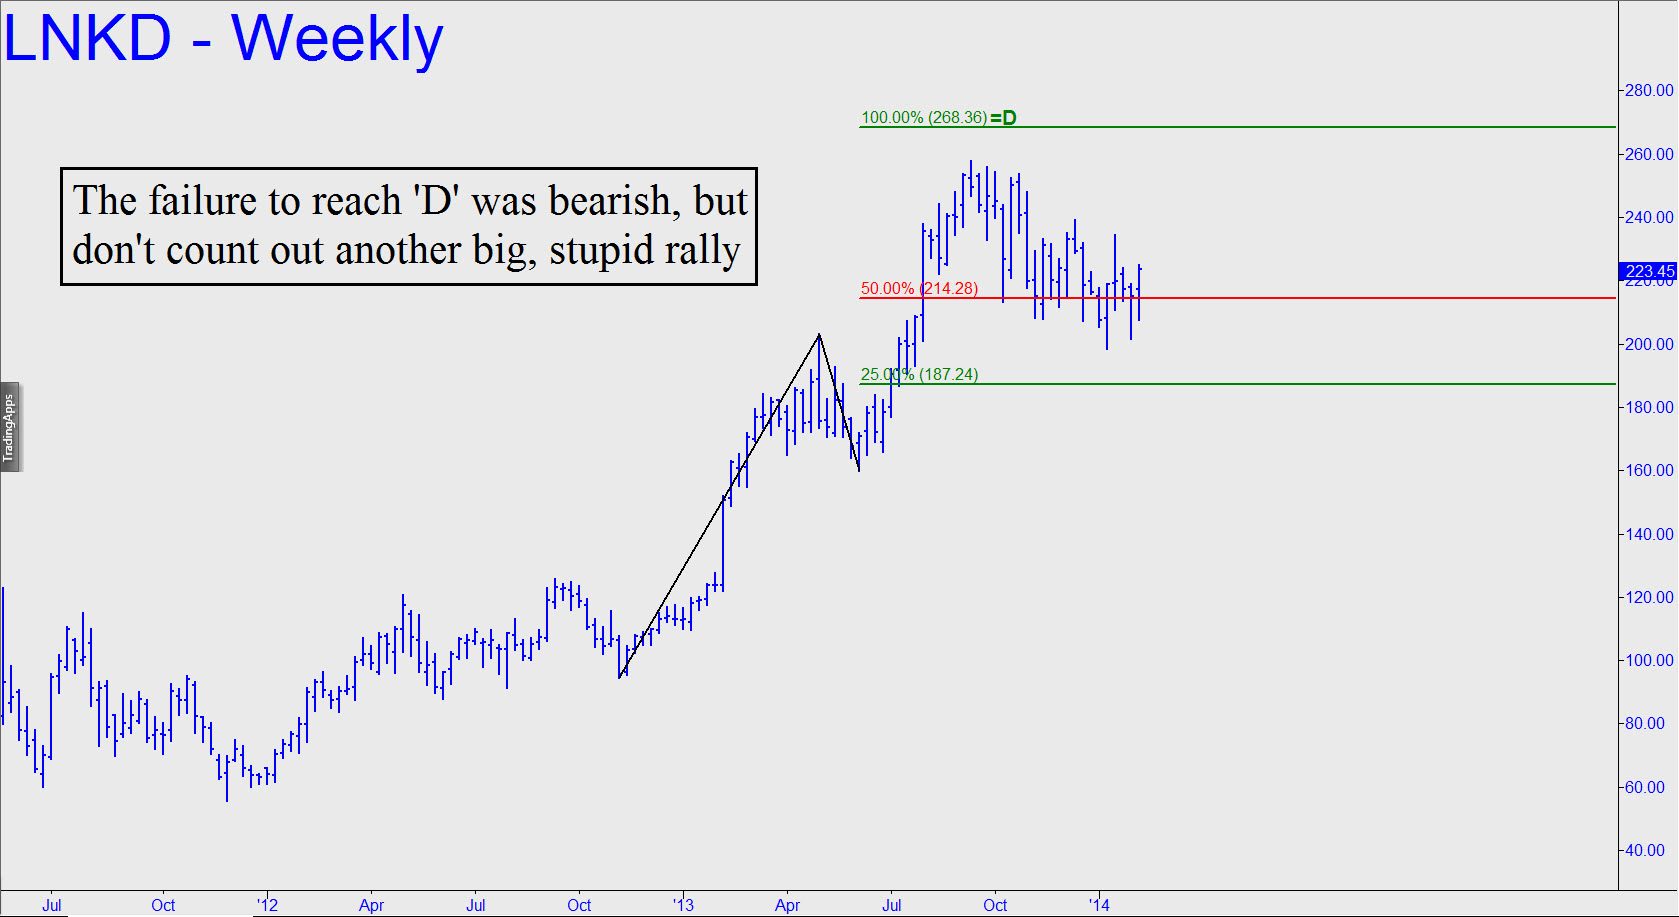
From a technical standpoint, the stock appears to have topped out in September $11 shy of a $268 target (see inset). Although I’d like to be able to say that that was the last gasp for LNKD’s undeserved bull market and that Wall Street has finally come to its senses, neither seems likely. Indeed, there is a good case to be made for another bull leg to $296. That would represent a 50% gain over last month’s correction low of 198. It’s clear that investors learned practically nothing from the dot-com collapse of 2000-2002. With LNKD priced at $296, they would get a second chance.