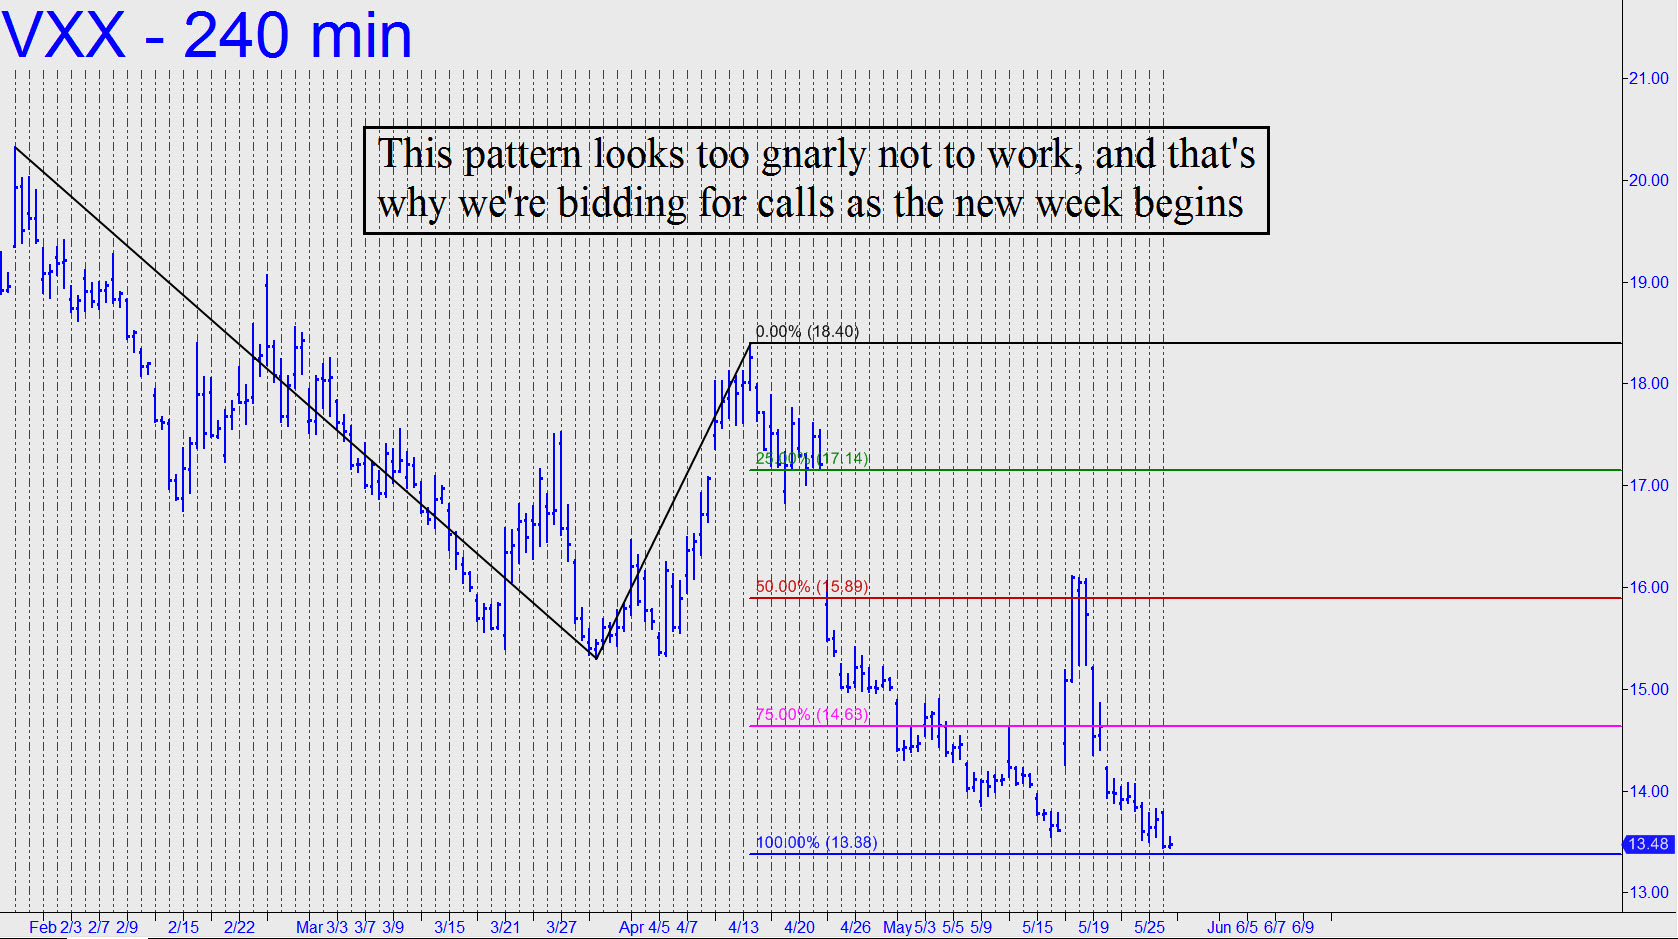
 I’m enthusiastic about the 13.38 target shown, since the pattern that produced it meets our Hidden Pivot criteria perfectly even though it may not be so obvious to others who use similar formations to trade and forecast. Indeed, the pattern is so enticing because it’s so gnarly, and that’s why we had a bid in for call options on Friday. The order went unfilled because the options traded no lower than 0.57, but I’ll recommend using a 0.40 bid for June 16 13.50 calls on Tuesday, since it could get filled if VXX falls closer to the target than the 13.45 low recorded in Friday. Do NOT pay up, since that’s not our style. Subscribers also hold four June 2 13.50 calls for 0.45 as a result of a trade posted to The Scoreboard last week. Originally I’d said I would track them only on The Scoreboard, but to simplify the accounting I’ve added them to this tout. ______ UPDATE (May 30, 7:13 p.m. ET): Raise the bid to 0.45 for four June 16 13.50 calls, day order. That’s a Hidden Pivot target for the options, and it looks like a promising spot to try bottom-fishing. VXX is sitting right on the 13.38 ‘hidden’ support, having exceeded it by 3 cents intraday. I still expect a bounce and would be surprised if it fails to materialize. If I’m wrong, we’ll probably see more downside to at least 12.47, or even 11.26 — significantly lower than this betting vehicle has ever traded before. _______ UPDATE (May 31, 6:56 p.m.): The puts we sought to buy traded no lower than 0.50, so there was nothing done on the order. Re-enter the bid ahead of Thursday’s opening and make it a day order. _______ UPDATE (Jun 1, 11:14 p.m.): We added four calls to the position at 0.45. Slippage beneath a 13.38 Hidden Pivot that looked very promising implies VXX could fall to 12.47, or even 11.26 (!) if it doesn’t turn from here. Even so, I will continue to recommend these bets because I like the odds. When it hits, it will likely pay AT LEAST 4-to-1. Also, we are not buying pricey (i.e., $1-$3) calls based on timing hunches, only to see those calls waste away to zero. Rather, we are typically acquiring options after they’ve shed 70% or more of their value, and doing so only at precise downside HP target supports that are clear and compelling.