 [Note: The Morning Line is published every Monday and Wednesday unless a significant event occurs in-between. Facebook and YouTube commentary, forecasts and trading ideas are aired on Monday’s and Wednesdays. RA]
The Dow Industrials ended the week with an 800-point Whoopee Cushion bounce that recouped two-thirds of a 1300-point loss suffered days earlier. The swoon, exhilarating as it may have seemed to traders, will do little to brighten an economic picture that has gone from boom to gloom since mid-summer. One might think the dark cloud of recession billowing over China and Europe these days would have caused investors to lower their expectations for the U.S. economy. However, evidence that they care even slightly about a global slowdown was nowhere to be discerned on Friday. Shares were up across-the-board, with the S&Ps tacking on a 40-point gain and the FAANG stocks in the rapacious grip of trade-desk madmen. Short-covering provided nearly all of the turbo-boost as it always does, warning bears still on the sidelines to stay put for the time being.
We’d fully expected the bounce to come from lower levels — specifically, from a 25,363 ‘Hidden Pivot’ target in the Dow that had looked certain to be achieved. Alas, the forecast missed by a not-so-trivial 380 points when the Indoos trampolined off 25,743. The jury is still out on this one, however, since 25,363 will remain a valid price objective in theory unless the rally exceeds 27,303. But it is usually a bullish sign when downtrending ABCD correction patterns fall short of their ‘D’ targets, as seems to have occurred here. Moreover, there is no reason to think that a deepening global downturn, impeachment mayhem and signs of a top in the U.S. economy will impair buyers’ bad judgment. For at the end of the day, the rally is not being driven by bullishness, but by urgent short-covering, a world awash in credit money, entrenched institutional mindset and a dearth of investment alternatives.
Love That Bad News!
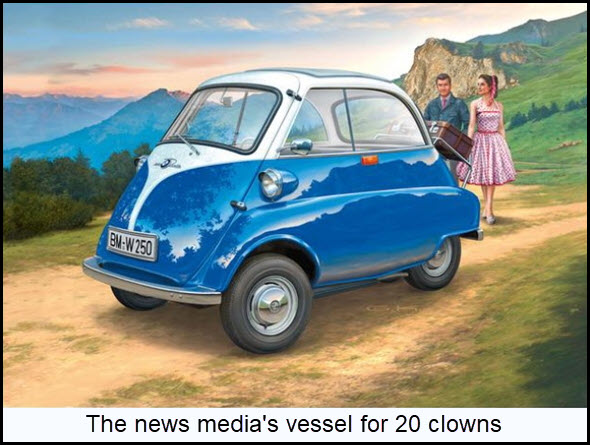
Although short-covering was the technical reason behind last week’s oversold bounce, the news media served up an explanation of its own that we can laugh at as we might the emergence of twenty clowns from an Isetta. So what was on investors’ tiny, febrile brains that might have justified their week-ending exuberance? Why, the prospect of more Fed easing, of course! Manufacturing, capital investment and consumer confidence falling off a cliff? No problem. As long as the securities world’s useful idiots continue to expect more easing, bad news will be greeted as good news. You say the Fed governors have promised no such thing? Well, they don’t need to as long as Powell, when addressing his masters on Wall Street, remains on his knees.
Concerning the technical picture, we are still literally banking on Apple shares to tell us when the fat lady might be ready to sing. The stock has an outstanding rally target at 243.68 (slightly revised from the 242.48 given here earlier) that looks very likely to be achieved. As long as AAPL keeps progressing toward it, the ten-and-a-half-year-old bull market will endure. Yes, this is at odds with the prediction above that the Dow will fall to at least 25,363. But because I am much more certain about Apple’s bullish chart than the Dow’s bearish one, I’ll place my bets on the former for now.
Comments on this entry are closed.
Dear Thomas,
When you say ” And, that reality (best house in a bad neighborhood) will, likely, prevail for quite some time to come–as the US stock market offers opportunity for appreciation versus sitting in cash somewhere?” then I guess it comes down to ones perception of what that word ‘reality’ actually means.
Yes I suspect we can mostly agree these elevated valuations are down to an abundance of easy money and a dearth of investment alternatives, hence share buybacks etc.
As to whether this current state of affairs is a sound and lasting ‘real’ basis for the valuation of anything, including the stock market, then I think that one’s up for discussion.
And let’s not fool ourselves and think all these money managers are just so stupid that they don’t know it themselves, but just like the subprime crisis, while the music’s playing you keep dancing.
So when the day comes that someone or something triggers the pack to consider just for a moment a look back at fundamental supports, oh you know things like the state of the global economy, geo-political affairs, investments that actually have something tangible underlying them, then the herd, like a flock of headless chickens, will panic for the bolting gate.
When that happens, then this current state of ‘reality’ will melt away overnight. When something can disappear overnight, I’m not certain just how ‘real’ that can be really.
As to the timing, yes I agree, who the hell knows huh? : )
You wrote, “One might think the dark cloud of recession billowing over China and Europe these days would have caused investors to lower their expectations for the U.S. economy.” Do you mean this in a qualitative sense? Or, are you saying, factually, that analysts have not, or done little to, reflect the “dark cloud of recession” in their current forecasts?
When the DaBoyz decide to put their foot on the necks to the shorts in an oversold market, naturally, the many of the shorts will begin to panic and cover. On this basis why should any of these participants care about “a global slowdown?” That reality is irrelevant when manipulation is ruling the day, correct?
How often, would you say, are ‘Hidden Pivot’ targets in the Dow missed by not-so-trivial, say, 300-400 points? Are there straight-forward explanations for such outcomes? Or, are these outcomes simple examples of why the Hidden Pivot devotee should always be prepared to be stopped out?
You wrote, “there is no reason to think that a deepening global downturn, impeachment mayhem and signs of a top in the U.S. economy will impair buyers’ bad judgment.” Mutual funds, most money managers, and hedge fund managers are required so mostly, if not entirely stay invested. Are you saying that their “bad judgment” refers to the high-flyers, over-owned growth stocks, and the FANG’s, for example?
When you say, “a world awash in credit money,” do you mean the (abundance of) easy money available due to low interest rates?
Finally, isn’t the key to what remaining upward bias exists the, as you mentioned, “dearth of investment alternatives?” And, that reality (best house in a bad neighborhood) will, likely, prevail for quite some time to come–as the US stock market offers opportunity for appreciation versus sitting in cash somewhere?
I see that Pan has done a good job answering most of your questions. Concerning how often Hidden Pivot targets miss, let alone by a mile, the answer is almost never. Skeptical? Then you should take a free two-week trial subscription to see for yourself how precisely accurate these targets are. Sign up at the top of my home page by leaving your name and email address — no credit card necessary. As for Hidden Pivot targets, they caught highs in the E-mini S&Ps and Comex Gold this morning by, respectively, one tick and two ticks. Subscribers actually used these target to make actual cash money.
Regarding the ‘dearth of investment alternatives’, you sound like you’ve never experienced a bear market before. You also seem to believe that a bull market can continue more or less indefinitely. Yes, it more or less can; but I am pretty sure we are in the ‘less’ stage of this one.